

Cash advance apps like Current and EarnIn can help when DailyPay is not an option at your job. DailyPay only works if your employer signs up for it, while these apps connect to your own bank account and get you money before payday.
Sometimes you need money and you need it now. You can use buy now, pay later apps, but an advance on pay you already earned is usually a simpler fit for a short gap.
See which app fits your paycheck, how fast the money lands and what it really costs.
Free every week. Unsubscribe anytime.
You’re in. Your cheat sheet is below. We sent a copy to your inbox too.
A peek insideYour sheet is below
The whole picture on one screen.

 EarnIn, Current, Grant and more
Your cash advance cheat sheet
| App | Max advance | Monthly cost | Free delivery | Fast delivery | What it needs |
|---|---|---|---|---|---|
| EarnIn | Up to $1,000 a pay period | $0, tips optional | 1 to 3 business days | About 30 minutes for $3.99 to $8.99 | Keeps your bank. Needs a regular pay schedule and a work email or work location |
| Current | Up to $1,000 | $0 | About 3 business days | Small fee | A $200+ payroll deposit into Current. Not in CT, MD, NV, WI or DC |
| Grant | $25 to $500 (first advance averages about $66) | $0, Grant Plus $9.99 optional | About 3 business days | About an hour for $2 to $21 | No payroll deposit needed. Not in CT, KS, MD, NV, RI, SC or WI |
| Brigit | Up to $500 | $8.99 to $15.99 | 1 to 3 days | Instant on Premium | Can advance automatically when your balance gets low |
Your own limit shows in each app after you connect your bank. Pay it back on time and most of them raise it.
If you’re strapped for time, I’ll go ahead and share the best DailyPay competitors, from the employer-sponsored pay apps to the cash advance apps you can download on your own.
What is DailyPay?
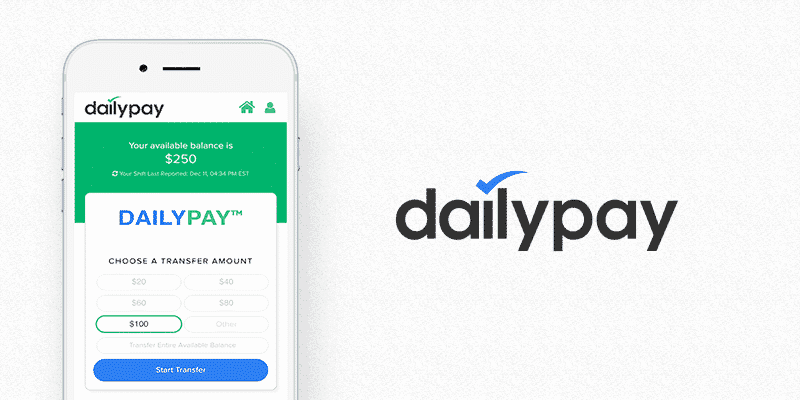
With DailyPay you can work and get paid today. Employees have access to their pay when they need it and in between paydays even. However, these types of daily pay apps are different than cash advance apps as your employer must sign up and offer DailyPay as a benefit.
But today we will go over DailyPay competitors.
Is there an app like DailyPay that does not need my employer?
Yes. DailyPay, PayActiv and FlexWage all depend on your employer offering them, but cash advance apps like Current and EarnIn work off your own bank account and paycheck instead. Grant and Tilt are the first two I would check.
Which app like DailyPay gives the most money?
Current lists a Paycheck Advance of up to $1,000 for eligible customers. EarnIn shows up to $200 a day and $1,000 per pay period. Grant and Tilt are both up to $500, and Klover says it can go as high as $750.
Do apps like DailyPay charge fees?
It depends on the app. With EarnIn there are no mandatory monthly fees or interest, and you choose what you want to pay. Tilt costs $8 a month after a 14-day free trial, and Grant has an optional express fee and a Plus plan. With the employer apps, the employer decides the fees.
Can I use more than one app at once?
You can have several installed, but every advance gets paid back from your next deposit, so stacking them leaves you short on the next paycheck. I would start with one, and add a second only if the first one does not cover what you need.
Best for getting cash the fastest
Top pick- Get up to $1,000 per pay period with no interest, ever
- No credit check required to get started
- Free standard transfers, $3.99 for Lightning Speed
Best paycheck advance, zero fees
No fees- Get up to $1,000 with no fees at all
- No credit check, just connect your paycheck
- Instant access with your Current account
Best for automatic cash advances
Auto-advance- Up to $500/advance, no credit check required
- No credit check, advances based on your income
- Automatic advances when your balance gets low
Best for no interest and no late fees
No late fees- Get $25 to $500 if you qualify, with no credit check
- No interest and no late fees
- Free standard delivery in 1 to 3 business days
Best DailyPay Competitors to Get Paid Early
These apps help you get your paycheck early and can help you get paid today.
Try these free mobile applications available in the App Store and Google Play Store, so you can borrow cash with ease:
1. Current
Best for: Anyone who wants a DailyPay alternative that doesn’t depend on their employer signing up.
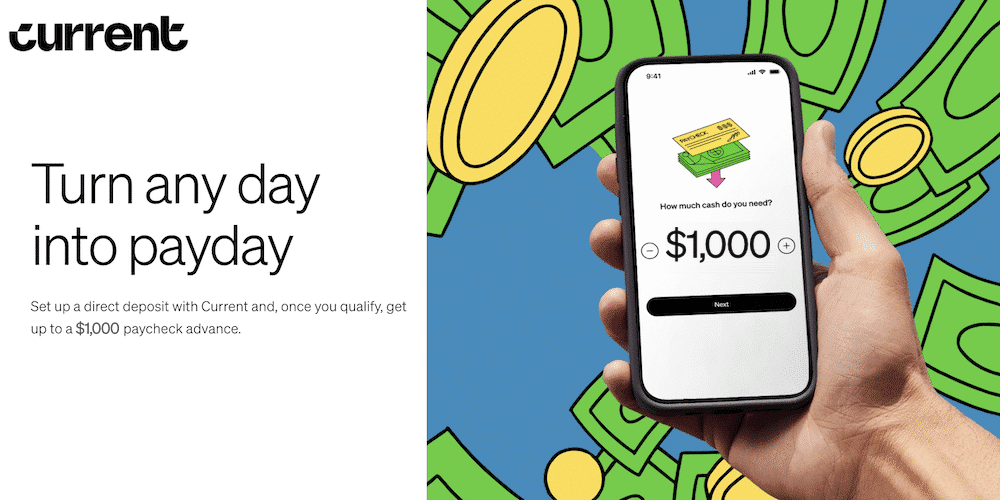
Current advances up to $1,000 through its Paycheck Advance for eligible customers. That is the highest cap on this list, and you open the account yourself.
To qualify you need at least one eligible payroll deposit of $200 or more in the last 35 days. With direct deposit you can also get paid up to 2 days early, and there is no credit check to open the account.
How it compares to DailyPay: DailyPay and Current both get you to your pay before the usual payday. The difference is setup. DailyPay needs your employer to offer it, and Current only needs your own paycheck deposit.
Watch out for: Your pay has to run through a Current account, so this is a bank switch and not just an app install. The advance is for eligible customers only.
Read our full Current review.
- Payday is just one tap away
- Get up to $1,000 before payday
- Get free instant access to your paycheck in advance
- No monthly fees, no catch
- Get $75 free with code WELCOME75 and $1,500 or more in direct deposits within 35 days
2. EarnIn
Best for: Workers who want a DailyPay alternative with no mandatory fees.
EarnIn lets you take up to $200 a day and up to $1,000 per pay period from pay you’ve already earned. There is no interest, no credit check and no mandatory fees.
Standard transfers are free. Lightning Speed gets the money to you in minutes and starts at $3.99. You choose what to tip, even if that’s nothing.
How it compares to DailyPay: EarnIn is the closest to DailyPay in spirit because both are built on pay you’ve already earned. The difference is that you set EarnIn up yourself, with a daily and a pay period cap, instead of waiting for your employer.
Watch out for: EarnIn has to verify your job, so gig or irregular income can be a harder fit.
Read our full EarnIn review.
- Access to your hard-earned cash right when you need it
- No hidden fees, no penalties, no waiting
- Get up to $1,000 of your paycheck per pay period
3. Brigit
Best for: Someone who wants a DailyPay alternative that’s quick to set up.
Brigit advances $25 to $500 with no credit check and no interest. It says it has 15M+ users, and sign-up takes about 2 minutes.
Express delivery costs $0.99 to $5.99, so check the price in the app before you confirm.
How it compares to DailyPay: DailyPay depends on your employer and Brigit doesn’t. Its $500 ceiling is under what Current and EarnIn can reach, but it’s a fair middle option if your employer has no pay app.
Watch out for: Getting the money fast is the part that costs. Express delivery runs $0.99 to $5.99.
Read our full Brigit review.
- Tap to get an advance within seconds
- Get up to $500
- No credit check is required and no interest
- Pay it back without hidden fees or “tips"
4. Grant
Best for: People who want a smaller DailyPay alternative and don’t want a credit check.
Grant advances $25 to $500 with no interest, no late fees and no credit check to apply. The average first advance is about $66, so you start small and work up.
Standard delivery is free and takes about 3 business days. Faster delivery costs extra.
How it compares to DailyPay: DailyPay lets employees reach earned pay when their employer offers it. Grant is an app you download yourself, so it works at any job. You give up size, and the free delivery is slower.
Watch out for: Grant isn’t available in every state, so check the app for yours before you count on it.
Read our full Grant review.
- Get $25 to $500 with no interest and no late fees
- No credit check to apply, average first advance is about $66
- Free standard delivery in about 3 business days, or express in about an hour for $2 to $21
- Grant Plus is $9.99/mo in the app, or email support for a free advance
5. PayActiv
Best for: Workers whose employer already offers PayActiv and who want a DailyPay alternative with a clear cap.
PayActiv lets you withdraw the greater of $500 or up to 50% of your earned wages. You can get paid today on money you’ve already earned, which helps you dodge late fees, overdraft fees and high-interest loans.
It only works if your employer offers PayActiv as a benefit.
How it compares to DailyPay: Like DailyPay, PayActiv gives you earned wages before payday. DailyPay gives access to your pay in between paydays. PayActiv puts a number on it: the greater of $500 or 50% of earned wages.
Watch out for: If your employer doesn’t offer PayActiv, you can’t use it. Ask HR first, or go straight to Current or EarnIn.
6. FlexWage
Best for: Employees whose job offers FlexWage and who want to compare it with a DailyPay alternative.
FlexWage usually gets you 70% to 80% of earned income with instant funding, through a reloadable card tied to your earned wages.
Your employer decides the fees, so the cost depends on where you work.
How it compares to DailyPay: FlexWage and DailyPay are the same kind of tool: an employer benefit that lets you reach pay you’ve already earned. FlexWage pays out on a reloadable card, and the share you can reach is 70% to 80%.
Watch out for: Fees are set by your employer, so ask before you use it. If your job doesn’t offer it, it isn’t an option.
7. Tilt
Best for: Anyone who wants a DailyPay alternative that skips the employer program and the credit check.
Tilt advances up to $500 with no application, no interest, no late fees and no credit check. It pays itself back automatically from your next direct deposit.
It costs $8 a month after a 14-day free trial. Tilt also has AutoSave, which sets money aside for you automatically.
How it compares to DailyPay: DailyPay needs your employer to enroll you. Tilt works from your own deposits, so you can sign up without talking to HR. The tradeoff is the $500 cap and the $8 a month after the trial.
Watch out for: Tilt isn’t available in Connecticut, Maine or Washington D.C. Cancel before day 14 if you only want to try it.
Read our full Tilt review.
- Get a no-fee and interest-free cash advance of up to $500
- Use AutoSave to automatically set money aside every week
- Costs $8 per month after a 14-day free trial
8. Cleo

Best for: Someone looking for a DailyPay alternative who doesn’t mind a subscription.
Cleo advances up to $250 with no interest, but only through Cleo Plus at $5.99 a month. You pick a repayment date between 3 and 14 days.
The free version gives you a budgeting tool, a digital wallet and a weekly quiz with chances to win cash rewards. It doesn’t include the advance. Taking an advance won’t affect your credit score.
How it compares to DailyPay: DailyPay is tied to your employer. Cleo isn’t, so it works at any job. You get a smaller cap, $250, and you pay $5.99 a month to use it.
Watch out for: The advance sits behind the paid plan. If you only borrow once in a while, $5.99 a month adds up.
Read our full Cleo review.

- You can earn cash back rewards and enjoy salary advances up to $250 with Cleo Plus ($5.99 a month)
- Robust free version that helps you budget, automatically save and track your spending
- You can earn interest on your savings
9. MoneyLion

Best for: Anyone who wants a DailyPay alternative from a full banking app.
MoneyLion offers Instacash advances of up to $500 at 0% APR once you link your checking account.
Its Spend account can get your paycheck up to two days early, and the app also bundles saving, investing and earning tools. The instant-delivery Turbo fee is 7.5%, capped at $14.99.
How it compares to DailyPay: DailyPay is an employer benefit. MoneyLion is an app you join yourself, so it works wherever you work. You trade employer setup for a $500 limit.
Watch out for: Turbo is the option that costs money. If you can wait, skip it.
Read our full MoneyLion review.
- The maximum advance is $500
- No interest. No monthly fee. No credit check
- Link your checking account to qualify for 0% APR cash advances
10. Klover
Best for: Someone who needs a bigger DailyPay alternative and has steady direct deposits.
Klover lists up to $750 for eligible users, and your first limit depends on your account. You need at least three consistent direct deposits in the past two months, with no gaps in pay from the same employer.
Klover advances come with no interest, no late fees and no credit check, but the funding can be slower than some competitors, and the optional express fees are relatively high.
How it compares to DailyPay: DailyPay gives employees their earned pay when the employer offers it. Klover is for people whose employer doesn’t, and it asks for a deposit history in return.
Watch out for: New or irregular income may not meet the three-deposit rule, and the express option is the costly one.
Read our full Klover review.
- Klover is an app that provides an advance of up to $200 on your next paycheck
- No mandatory fees
- An optional express fee from $2.99 to $20.78 to receive funds faster
Cash Advance FAQs
Here are a few more questions people ask when they are looking for an app like DailyPay:
Several of the cash advance apps on this list say they do not run a credit check, including Tilt, Grant and Brigit. Check each app’s section above, because the rules are different for every one.
Not quite. DailyPay, PayActiv and FlexWage give you access to wages you have already earned, and your employer has to offer them. Cash advance apps like Current and EarnIn work from your own bank account instead, so you can use them without asking your employer.
Most of these apps take the money back automatically. With Tilt you pay it back when your next direct deposit lands, and with Cleo you pick a repayment date between 3 and 14 days.
Cash advance apps are not free money, since you pay every advance back. If you want to earn instead, we have a list of apps that pay you.
External resources, so you don’t have to do the research:
1) Have you lost your job? You can file for unemployment. While you wait for it to kick in, FlexWage alternatives, PayActiv alternatives and $100 loan instant apps are worth a look.
2) Looking to earn money? We have two articles about this, one for people looking for full-time online jobs and another for people looking for part time income (the gig economy).
3) Worried about bills? Here is an article from our team on ways to save money on groceries. Credit card companies and some banks are also delaying payments, waiving fees, and removing interest charges. Read about it here. You can get out ahead of these problems.
4) Trying to stretch your budget? Check out our guide on living cheap. Maybe you already know it all, but maybe there are some tidbits in there to help.
Borrow Responsibly when Using Apps Like DailyPay
If you’re like most people, any new financial need or demand makes you irritated and tense. Most cash advance apps can help you meet your immediate demands without delay or having to seek secured personal loans. Since you’re likely unready for financial emergencies and each additional financial obligation can put you on edge.
There are several advantages of getting a cash advance via an app rather than going to a local bank or pawnshop to try and get quick cash. Even though there are many lending institutions in each city today, you may not be aware of all the nuances, interest rates and fees among them.
Every potential borrower must understand that he or she is fully responsible for any loan or cash advance obtained. This money should not be taken for granted, since it will only be used for a brief period of time.
Finally, such small amounts of loaned money can’t accommodate long-term financial objectives. Consider alternative ways to finance your long-term goals and needs, or try to increase your income potential with side hustles.
With that said, good luck with borrowing money with these apps like DailyPay!
See which app fits your paycheck, how fast the money lands and what it really costs.
Free every week. Unsubscribe anytime.
You’re in. Your cheat sheet is below. We sent a copy to your inbox too.
A peek insideYour sheet is below
The whole picture on one screen.
EarnIn, Current, Grant and moreYour cash advance cheat sheet
| App | Max advance | Monthly cost | Free delivery | Fast delivery | What it needs |
|---|---|---|---|---|---|
| EarnIn | Up to $1,000 a pay period | $0, tips optional | 1 to 3 business days | About 30 minutes for $3.99 to $8.99 | Keeps your bank. Needs a regular pay schedule and a work email or work location |
| Current | Up to $1,000 | $0 | About 3 business days | Small fee | A $200+ payroll deposit into Current. Not in CT, MD, NV, WI or DC |
| Grant | $25 to $500 (first advance averages about $66) | $0, Grant Plus $9.99 optional | About 3 business days | About an hour for $2 to $21 | No payroll deposit needed. Not in CT, KS, MD, NV, RI, SC or WI |
| Brigit | Up to $500 | $8.99 to $15.99 | 1 to 3 days | Instant on Premium | Can advance automatically when your balance gets low |
Your own limit shows in each app after you connect your bank. Pay it back on time and most of them raise it.